During the third quarter, East Capital Global Frontier Markets returned 3.9%, significantly ahead of the MSCI Frontier Markets Index, which fell 0.3%. This marked another strong period for the strategy, lifting year-to-date performance to 17.1%.
Once again, Africa was the strongest contributor to portfolio performance, with Kenya and Nigeria being the two largest country contributors. In Kenya, it was the banks that were the standout performers. Equity Group gained 34% while KCB Group gained 22%, both supported by an exceptionally strong half-year reporting season. Equity Group increased its profit after tax by 32%, while loan growth of 18.9% and deposit growth of 21.4% comfortably exceeded management’s full-year guidance. KCB Group reported a 20.8% increase in pre-tax profit, setting a record level, with loan and deposit growth also exceeding guidance. Return on equity reached 21.1%, while the interim dividend was increased by 50%. Despite their strong share price performance, the banks are trading at just 4.5x and 3.9x 2026e earnings and at 1.0x and 0.75x book value. Meanwhile they are generating returns on equity above 20%, and offering dividend yields of 6.3% and 6.8%, respectively.
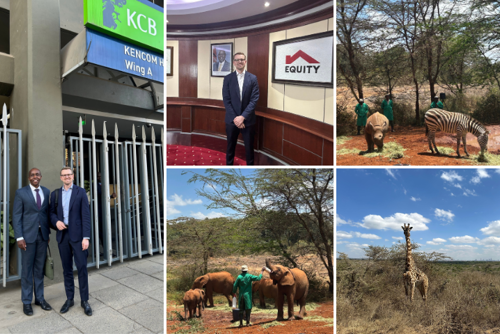
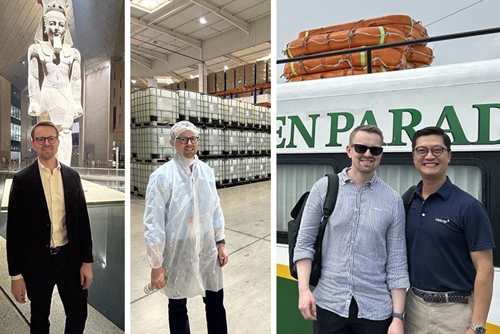
Our research trip to Nairobi towards the end of the quarter reinforced our constructive view on Kenya. Meetings with listed companies, the IMF and the National Treasury indicated a resilient economy and a notably positive mood on the ground. Foreign exchange reserves have improved to approximately seven months’ worth of import cover, which provides a cushion against higher fuel prices. Meanwhile, private-sector credit has declined from around 40% of GDP a decade ago to roughly 30%, leaving considerable room for renewed lending growth.
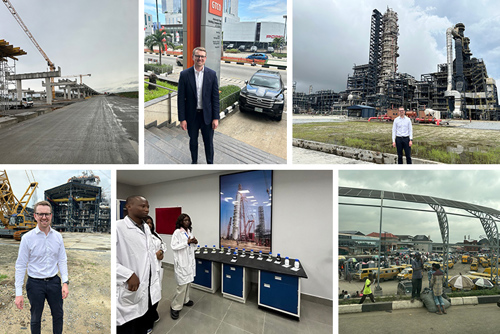
Our visit to Nairobi also coincided with preparations for the groundbreaking of the Dangote-backed East Africa Oil Refinery in Lamu. This USD 16-17 billion project envisages processing 700,000 barrels of oil per day, supplying fuel across East and Central Africa. It broadly replicates the model we discussed following our visit to the Lagos refinery last quarter. The project remains at a very early stage, but if it is successfully executed, it could have significant implications for Kenya and the wider region, including financing opportunities for local banks and suppliers.
Safaricom, Kenya’s largest telecommunications company and operator of the M-Pesa mobile-money platform, saw it share price rise by 10% reaching 12.3x 2026e earnings, with a 7% dividend yield. In September, the High Court nullified the government’s sale of a 15% stake in Safaricom to Vodacom, a decision that both parties are challenging. The dispute concerns the ownership structure rather than the underlying business itself, which continues to develop well, with the Ethiopian operation rapidly approaching EBITDA breakeven.
Nigeria also had another strong quarter. Zenith Bank gained 26%, while Guaranty Trust Holding rose 11%. Both remain inexpensive, trading at 4.2x and 4.8x 2026e earnings and 1.0x and 1.2x book value respectively, while generating returns on equity of 25% and 28% and offering dividend yields of 10.4% and 11%. Sentiment was further supported by the Central Bank’s 350-basis-point policy-rate cut, bringing it down to 23% and by Nigeria’s return to FTSE Russell’s Frontier Market classification, which helped attract renewed foreign and institutional interest.
The deepening of Nigeria’s capital market is also gathering pace. In September, Dangote Petroleum Refinery launched an IPO targeting approximately USD 1.6 billion at a valuation of around USD 48 billion. If completed as planned, this would be the largest IPO in African history, representing an important milestone for the local equity market.
Outside of Africa, our Georgian banks delivered another very strong quarter. Lion Finance Group gained 24.4%, while TBC Bank returned 18.1%. Both banks benefit from resilient domestic franchises alongside an increasingly meaningful regional expansion: Lion Finance does this through Ameriabank in Armenia, and TBC does it through its digital operations in Uzbekistan. This provides an additional growth opportunity and greater earnings diversification. Profitability remains exceptional, with second-quarter returns on equity of approximately 27% and 24%, respectively.
Halyk Bank in Kazakhstan was another meaningful contributor, gaining 20.5% during the quarter and 37.5% year to date. Its Second-quarter return on equity reached an impressive 28.6%, yet its shares still trade at only around 1.0x the expected 2026 book value, while offering a dividend yield of approximately 11%. Its dominant domestic franchise, high profitability and attractive capital distributions continue to underpin our investment case.
The Middle East remained relatively quiet, with most holdings broadly trading sideways amid continued uncertainty about the regional backdrop. Nevertheless, our search for company-specific opportunities continued. In Saudi Arabia, we initiated a position in Almasar Alshamil, an education company focused on special-care services. The company delivered approximately 22% growth in the first half of the year and has a strong expansion pipeline, supported by favourable demographics and significant unmet demand. Based on our 2026 estimates, the shares are trading at around 14x earnings, which we consider to be reasonable, given the potential for approximately 20% annual revenue growth over the coming years. In the UAE, our portfolio of high-quality, reasonably valued companies stabilised following the volatility earlier in the year. While the regional outlook remains difficult to assess, the calmer market environment was welcome.
On the negative side, PNJ, our long-standing Vietnamese jewellery retailer holding, was affected by an unexpected diamond-smuggling investigation involving the former head of its metal purity testing subsidiary. Due to the limited information available and the difficulty of quantifying the company-specific risk, we exited the position promptly. The authorities subsequently concluded that the smuggled diamonds had not entered PNJ’s retail system. However, the episode resulted in significant provisioning related to customer repurchases and an eventual share-price collapse. This event illustrates our pragmatic approach to risk management: when the potential outcomes become unusually difficult to assess, we prefer to limit exposure and redeploy capital into opportunities with a cleared risk-reward profile. As a result, the overall portfolio impact was minimal.
Frontier markets continue to perform well in 2026, although we remain mindful that markets rarely move in a straight line. Rather than extrapolating recent returns, we continue to focus on monitoring current holdings and identifying new opportunities. During the quarter, the team met companies across the Middle East, Vietnam and Kenya through conferences, company visits and one-to-one meetings.
We are also seeing greater-than-usual investor interest in frontier markets, as global equity portfolios are becoming more and more concentrated in a small number of companies and themes, particularly those related to artificial intelligence. Frontier markets offer a differentiated source of growth with domestic earnings as the main driver. They also have low correlations between individual markets and structural trends such as financial deepening, formalisation, urbanisation and rising consumption.
Despite the strong performance of the strategy this year and over the past three years, the portfolio trades at a 12-month forward P/E of just 6.8x. Our holdings also continue to offer mid-teens earnings growth, predominantly supported by structural rather than purely cyclical drivers. We therefore believe that, as we enter the final quarter of the year, the combination of undemanding valuations, diversified growth sources and disciplined stock selection continues to provide an attractive risk-reward profile.
Performance in USD net of fees.
The information in this document should not be considered investment advice and should not be used as the sole basis for an investment decision. Please read the Prospectus and the KID, which are available on the fund page. This publication is not directed at you if we are prohibited by any law in any jurisdiction from making this information available to you and is not intended for any use that would be contrary to local laws or regulations. Every effort has been made to ensure the accuracy of the information, but it may be based on unaudited or unverified figures or sources.